Category Archives: Marketing

Navigating Product Liability: Know Your Rights & Recourse

Have you ever wondered what happens when a product you purchased causes harm or injury? Whether it’s a malfunctioning appliance, a defective car part, or a hazardous toy, dealing with the aftermath of a faulty product can be daunting. 

Product liability laws are designed to protect consumers like you in such situations, ensuring that you have recourse when products fail to meet safety standards or come with undisclosed risks. 

In this article, we’ll delve into the intricacies of product liability, helping you understand your rights and navigate the legal landscape.

As you explore the complexities of product liability, it’s crucial to have access to reliable resources and guidance. That’s where ConsumerShield comes in. ConsumerShield is dedicated to helping individuals understand their rights and navigate the legal complexities of defective product lawsuits. Their mission is to empower consumers with the knowledge and resources needed to take on these complex legal battles and fight for the justice they deserve.

What is Product Liability?

Product liability refers to the legal responsibility of manufacturers, distributors, and sellers for injuries and damages caused by defective products. These flaws can show in a variety of ways:

  • Manufacturing defects: These occur during the production process, resulting in a product that deviates from its intended design.
  • Design defects: These flaws exist in the product’s blueprint or conception, making it inherently unsafe even when manufactured correctly.
  • Marketing defects: Also known as failure to warn, these involve inadequate instructions or warnings about potential risks associated with the product’s use.

As a consumer, you have the right to expect that products you purchase are safe when used as intended. When this expectation is not met, you may have grounds for a product liability claim.

The Legal Landscape of Product Liability

In the United States, product liability laws vary by state but generally adhere to certain principles. To establish liability in a product liability case, the following elements must typically be proven:

  • The product was defective or unreasonably dangerous.
  • The defect caused harm or injury.
  • The product was utilized as intended or in a reasonably anticipated manner.

Manufacturers, distributors, and retailers can all be held accountable for product defects, depending on their role in bringing the product to market. Recent trends in product liability litigation include an increased focus on consumer safety and stricter regulations to prevent harm.

Recent trends in product liability litigation indicate a concerning rise in consumer injuries caused by defective products. According to the Consumer Product Safety Commission (CPSC), there were approximately 240,000 toy-related injuries treated in U.S. hospital emergency rooms in 2020 alone. This alarming statistic underscores the pressing need for stringent product safety measures and effective consumer protection laws.

What actions should you take if a faulty product affects you?

If you or a loved one has been harmed by a defective product, it’s essential to take immediate action to protect your rights:

  • Document the Incident: Keep records of the product, any injuries sustained, medical treatment received, and any communication with the manufacturer or seller.
  • Preserve Evidence: Preserve the defective product, if possible, as well as any packaging or instructions that accompanied it.
  • Seek Medical Attention: Prioritize your health and well-being. Seek medical attention for any injuries resulting from the defective product.

Understanding Compensation and Recourse

In product liability cases, compensation may be available to cover various damages, including medical expenses, lost wages, pain and suffering, and punitive damages. The amount of compensation awarded depends on factors such as the severity of the injuries, the degree of negligence involved, and the jurisdiction’s laws.

Product liability lawsuits are prevalent across various industries, with the automotive sector experiencing a significant share of legal actions. According to the Insurance Information Institute, the automotive industry accounts for the highest number of product liability lawsuits, often involving defective airbags, brakes, and tires. These cases highlight the profound impact that faulty products can have on consumer safety and underscore the importance of holding manufacturers accountable for ensuring the quality and safety of their products.

Conclusion

In conclusion, navigating product liability can be complex, but understanding your rights is crucial. If you’ve been affected by a defective product, don’t hesitate to seek legal guidance. Remember, you have the right to pursue compensation for injuries and damages caused by unsafe products.

Don’t let a defective product derail your life. Take action immediately to safeguard yourself and your loved ones.

When Disaster Strikes: Leading Data Recovery Services for Hard Drives, SSDs, and Beyond

Data loss can be a heart-wrenching experience. Whether it’s precious photos, important documents, or irreplaceable business files, losing access to your digital life can feel devastating. But before despair sets in, know this: there’s hope. leading data recovery services for hard drives, SSD, and other devices possess the expertise and technology to potentially retrieve your lost data, even in seemingly hopeless situations.

This article delves into the world of data recovery, unveiling the leading services and guiding you through the process of choosing the right option for your specific needs.

Understanding Data Loss:

Data loss can occur due to various factors, ranging from accidental deletion and formatting to physical damage like water spills or electrical surges. Even logical issues like corrupted files or faulty operating systems can contribute to data inaccessibility.

Types of Data Recovery Services:

Not all data loss scenarios are created equal. Leading services offer specialized solutions categorized by device type, complexity, and urgency. Here’s a breakdown:

  • Hard Drive Recovery: Traditional spinning disks are susceptible to mechanical and logical failures. Services recover data from physically damaged platters, corrupted file systems, and deleted files.
  • SSD Data Recovery: Solid-state drives present new challenges due to their flash memory architecture. Leading services employ advanced techniques to overcome limitations and achieve data recovery.
  • RAID Recovery: Redundant Array of Independent Disks (RAID) configurations offer data redundancy, but complexity increases risk. Services specialize in retrieving data from failed RAID systems, preserving redundancy if possible.
  • Mobile Device Recovery: Smartphones and tablets hold critical personal data. Services recover lost photos, messages, contacts, and more from damaged or formatted devices.
  • Data Recovery from Other Devices: Leading services often extend their expertise to SD cards, USB drives, servers, and even tapes, offering comprehensive solutions for diverse storage needs.

Choosing the Right Data Recovery Service:

With numerous options available, selecting the right service requires careful consideration. Here are key factors to evaluate:

  • Reputation and Experience: Opt for companies with a proven track record, positive customer reviews, and established industry presence.
  • Expertise and Specialization: Ensure the service possesses expertise in recovering data from your specific device type and problem scenario.
  • Success Rates and Guarantees: Many services offer success rate estimates and data-no-recovery-no-fee guarantees, providing transparency and reducing financial risk.
  • Cost and Transparency: Compare pricing models and get detailed quotes upfront. Avoid hidden fees and ensure you understand the complete cost before proceeding.
  • Data Security and Privacy: Choose a service with robust security practices and strict data confidentiality policies to protect your sensitive information.
  • Customer Support and Communication: Clear communication and timely updates are crucial during the recovery process. Opt for services with responsive and knowledgeable customer support teams.

Leading Data Recovery Service Providers:

While this list isn’t exhaustive, here are some of the most respected and trusted data recovery service providers:

  • DriveSavers: Industry leader with global reach, offering advanced services for all devices and scenarios.
  • Stellar Data Recovery: Renowned for its expertise in SSD and RAID recovery, with diverse service options.
  • OnTrack: Global presence with a focus on customer service and customized solutions.
  • Secure Data Recovery Services: Specializes in high-security data recovery for businesses and government agencies.
  • CBL Data Recovery: Offers affordable and transparent data recovery services for various devices.

Remember: Acting quickly increases the chances of successful data recovery. Stop using the affected device immediately and avoid running recovery software yourself. Contact a reputable data recovery service as soon as possible for the best chance of retrieving your valuable data.

Additional Tips:

  • Regularly back up your data to prevent future data loss incidents.
  • Invest in reliable storage solutions and disaster recovery plans.
  • Stay informed about data security best practices to proactively minimize risks.

Data loss can be stressful, but by understanding the available options and choosing the right data recovery service, you can significantly increase your chances of reclaiming your digital life. Remember, with expert help and timely action, data loss doesn’t have to be a permanent disaster.

Unlock Efficiency & Expertise: Your Guide to Outsource Web Development

Unlock Efficiency & Expertise: Your Guide to Outsource Web Development

Web development is becoming more and more outsourced. It works well for building an online presence and producing minimum viable products (MVPs) fast. Because not all businesses can manage web development internally, outsourcing is essential. It opens up access to bespoke software, even for smaller companies.

We’ll talk about effective outsourcing best practices in this post. We’ll go over the advantages, the detailed procedure, and how to choose the best supplier. We’ll also contrast global IT outsourcing solutions. Let’s dive in!

Why Do Companies Outsource?

According to Deloitte’s study, there are three main reasons why companies outsource, albeit these may vary depending on their area of expertise: 

  • Cost savings (59%)
  • Focus on core competencies (57%)
  • Capacity issues (47%)

Outsourcing web development allows small and medium-sized businesses to use essential technologies without having to start from scratch, which may be quite beneficial. It offers access to a larger talent pool while reducing labor costs.

72% of IT organizations currently use outsourcing, since the practice is becoming more and more common. For non-technical entrepreneurs with creative ideas, outsource web development company is essential. It ensures professional and timely application development. Using a website crawler tool can help find reliable outsourcing partners.

After receiving the application, you can either transition to an in-house team or continue scaling the outsourced team for cost-effectiveness.

Many firms opt for international outsourcing to access experienced professionals and reduce risks and MVP design costs.

Benefits of Outsourcing

For your business, there are a lot of benefits to outsourcing web development.

  • Cost savings. Outsourcing can save companies 20-75% of the estimated budget, thanks to favorable rates and eliminating hiring and training costs.
  • Access to talent. Through outsourcing, you may access a broader pool of experts and make sure the right one is assigned to your project.
  • Scalability. Outsourcing allows for quicker project scaling as experienced teams can add specialists efficiently, reducing resource allocation compared to in-house hires.
  • Risk reduction. Outsourcing comes with a dedicated project manager who handles planning, communication, and issue resolution, ensuring adherence to timelines and contract obligations.
  • Project security. IT outsourcing companies implement security measures like Non-Disclosure Agreements and secure repositories, safeguarding your project and ideas.
  • Focus on core competencies. Outsourcing frees entrepreneurs to focus on profit-generating tasks like design, marketing, and sales, streamlining project approval and review processes.
  • Ongoing support. Outsourcing partners often commit to long-term relationships, offering support beyond tech development, such as market research and competitor analysis.
  • Accelerated development. Outsourcing speeds up project organization and development processes, leveraging specialized methodologies and access to innovative technologies.

Factors Affecting the Cost of Outsourcing

Many variables affect how much outsourced web development and design costs:

  1. Project complexity and tech stack. More complex projects with advanced technology requirements typically incur higher costs due to the expertise and resources needed.
  2. Number of specialists. The size and scope of the project determine the number of specialists required, impacting overall costs. More specialists mean higher expenses.
  3. Hourly rates. Costs are greatly influenced by the hourly rates of experts in the nation that is being outsourced. Rates change based on the economic conditions and degree of competence in the area.
  4. Time frame. Expenditures are impacted by the project’s timetable; shorter deadlines sometimes call for more resources, which might result in higher expenditures.

Businesses can more effectively estimate and plan their budgets for outsourced web development and design projects when these factors are taken into account.

Businesses may gain efficiency and knowledge via web development outsourcing, handling complex projects more rapidly and economically. Gaining an understanding of elements such as project complexity, hourly rates, time constraints, and unique requirements facilitates decision-making and helps to optimize the advantages of outsourcing. Outsourcing is an essential instrument in the current digital era that helps firms achieve some objectives, including cost reduction, talent pool expansion, and project schedule acceleration. Accepting outsourcing improves business performance, fosters creativity, and concentrates on essential competencies.

GDPR Principle 2: Purpose Limitation

The General Data Protection Regulation (GDPR) is a comprehensive set of data protection rules designed to safeguard the privacy and personal data of individuals within the European Union (EU) and the European Economic Area (EEA). One of the fundamental principles underpinning GDPR is the Purpose Limitation principle, which plays a crucial role in ensuring that personal data is processed with transparency and accountability.

GDPR Text on Purpose Limitation

The Purpose Limitation principle is explicitly outlined in Article 5(1)(b) of the GDPR, stating that personal data must be collected for specified, explicit, and legitimate purposes and not further processed in a manner that is incompatible with those purposes.

Understanding the Purpose Limitation Principle

The Purpose Limitation principle emphasizes the importance of clearly defining the purposes for which personal data is collected and processed. Organizations are required to be transparent about their data processing activities and ensure that any subsequent use of the data aligns with the originally stated purposes.

Importance of Purpose Limitation

  1. Enhancing Transparency: Purpose limitation enhances transparency by requiring organizations to clearly communicate the reasons for collecting personal data. This transparency fosters trust between data subjects and data controllers.
  2. Minimizing Data Collection: By specifying the purposes for data collection, organizations are encouraged to collect only the necessary information. This minimization of data collection helps protect individuals’ privacy and reduces the risk of unauthorized or excessive data processing.
  3. Preventing Unlawful Processing: The Purpose Limitation principle acts as a safeguard against unlawful processing of personal data. Any processing that deviates from the originally stated purposes without legal basis is considered a violation of GDPR.

Examples of Purpose Limitation in Practice

  1. E-commerce Transactions: An e-commerce platform collects customer data for the purpose of processing orders and managing customer accounts. If the same data is later used for unrelated marketing purposes without the explicit consent of the customers, it would violate the Purpose Limitation principle.
  2. Employee Records: In a corporate setting, employee data collected for payroll and human resources purposes should not be used for marketing campaigns without the explicit consent of the employees.
  3. Legal Expert Perspective: According to privacy law expert the Purpose Limitation principle serves as a cornerstone in data protection laws, emphasizing the need for organizations to be clear and specific about their data processing purposes.
  4. Case Study: Facebook and Data Misuse: The Cambridge Analytica scandal involving Facebook in 2018 highlighted the consequences of failing to adhere to the Purpose Limitation principle. Facebook’s user data was misused for political profiling, leading to increased scrutiny and legal actions.

The Purpose Limitation principle in GDPR is a critical element in ensuring responsible and ethical handling of personal data. By setting clear boundaries on data processing purposes, organizations can build trust with individuals and contribute to a more secure and privacy-centric digital environment. Adherence to this principle not only aligns with legal requirements but also reflects a commitment to respecting the rights and privacy of individuals.

Why is Purpose Limitation Important?

Data protection is a paramount concern in the digital age, and the Purpose Limitation principle, a key tenet of the General Data Protection Regulation (GDPR), plays a pivotal role in safeguarding individuals’ privacy. The importance of Purpose Limitation lies in several critical aspects:

Transparency and Trust

Purpose Limitation fosters transparency by requiring organizations to explicitly state why they collect personal data. This transparency builds trust between data subjects and data controllers, as individuals are informed about the exact purposes for which their data will be used.

Minimization of Data Collection

By specifying the purposes for data collection, organizations are compelled to collect only the necessary information. This minimization of data collection is fundamental to protecting individuals’ privacy, as it reduces the risk of storing excessive or irrelevant data.

Legal Compliance and Accountability

Adhering to the Purpose Limitation principle is a legal requirement under GDPR. Organizations that fail to define and adhere to specific data processing purposes risk legal consequences, including fines and other sanctions. This principle reinforces accountability in data processing practices.

Prevention of Unauthorized Processing

Purpose Limitation acts as a safeguard against unauthorized or unlawful processing of personal data. Any deviation from the initially stated purposes without a legal basis is considered a breach of GDPR, reinforcing the protection of individuals’ rights.

How Do You Specify the Purpose to Data Subjects?

Privacy Policies and Notices

Organizations can specify the purpose of data processing to data subjects through clear and easily accessible privacy policies and notices. These documents should articulate the reasons for collecting data, the intended uses, and any third parties with whom the data may be shared.

Consent Mechanisms

Obtaining explicit consent from data subjects is a crucial step in specifying the purpose. Consent forms should clearly outline the intended purposes of data processing, and individuals should have the option to opt in or out based on their preferences.

Communication and Education

Regular communication and educational initiatives help inform data subjects about the purpose of data processing. This can include newsletters, email updates, and educational materials that emphasize the organization’s commitment to transparent and responsible data handling.

User-Friendly Interfaces

Designing user interfaces that clearly communicate the purpose of data collection enhances the overall user experience. Simple and straightforward language should be used to convey the reasons behind data collection, fostering user understanding and trust.

Can Data Be Used for Multiple Purposes?

While the Purpose Limitation principle advocates for specific, explicit, and legitimate purposes for data collection, there are instances where data can be used for multiple purposes. However, such usage must adhere to certain conditions:

Informed Consent

If data subjects have provided explicit consent for multiple purposes, organizations may use the data for those specified purposes. Consent should be obtained separately for each distinct purpose to ensure clarity.

Compatibility with Original Purpose

Using data for additional purposes should be compatible with the original purpose of collection. If there is a reasonable expectation that the new purpose aligns with the original intent, it may be permissible.

Legal Basis

Organizations can use data for multiple purposes if there is a legal basis for doing so. Legal obligations or the necessity of data processing for the performance of a contract are examples of such bases.

Robust Data Governance

Implementing robust data governance practices ensures that data is handled responsibly and ethically. Organizations should have clear policies and procedures in place to assess and manage the compatibility of using data for multiple purposes.

The Purpose Limitation principle serves as a cornerstone in building a trustworthy and accountable data ecosystem. By emphasizing transparency, minimizing data collection, and ensuring that data is used for specified purposes, organizations can not only comply with legal requirements but also foster a culture of responsible data handling that respects individuals’ privacy rights. Striking the right balance between data utility and privacy is essential for creating a digital landscape that prioritizes both innovation and the protection of personal information.

What Happens if the Purpose Changes Over Time?

The Purpose Limitation principle, a cornerstone of the General Data Protection Regulation (GDPR), dictates that personal data should be collected for specific, explicit, and legitimate purposes and not processed further in ways incompatible with those original purposes. However, real-world scenarios often involve changes in business strategies, technological advancements, or unforeseen circumstances that may necessitate a shift in data processing purposes. Understanding the implications of such changes is crucial.

Legal Consequences

Changing the purpose of data processing without legal justification can lead to severe consequences. GDPR imposes strict penalties for non-compliance, including fines that can amount to a percentage of the organization’s global annual turnover. Legal actions and reputational damage may also follow, especially if the changes result in privacy breaches.

Informed Consent

If the purpose change aligns with the original consent given by data subjects, organizations may proceed. However, obtaining new and explicit consent for the revised purposes is a recommended practice. This ensures that data subjects are informed and have the opportunity to opt in or out based on the updated context.

Transparency and Communication

Maintaining transparency is key when the purpose changes over time. Organizations should communicate such changes clearly and promptly to data subjects through updated privacy policies, notices, or direct communication channels. Transparency fosters trust and helps mitigate the potential negative impact of purpose changes on individuals.

What Is a Compatible Purpose?

A compatible purpose refers to a secondary use of personal data that is reasonably expected and aligned with the original purpose for which the data was collected. GDPR recognizes compatible purposes as legitimate grounds for further processing without the need for explicit consent, provided certain conditions are met.

Criteria for Compatibility

GDPR outlines several criteria to determine the compatibility of a new purpose with the original one. These include the relationship between the purposes, the nature of the data, the context of the processing, the safeguards in place, and the reasonable expectations of data subjects.

Examples of Compatible Purposes

  1. Analytics and Research: Using collected customer data for statistical analysis to improve products or services may be considered a compatible purpose, as long as it aligns with the initial purpose of providing those products or services.
  2. Security Measures: Employing personal data for enhancing cybersecurity or fraud prevention is often considered compatible if it serves to protect the legitimate interests of the organization and its users.
  3. Legal Expert Perspective: According to privacy law expert determining compatibility requires a careful assessment of the specific circumstances. Factors such as the nature of the data, the context of processing, and the expectations of data subjects play a crucial role.
  4. Study on Data Processing Changes: A study conducted by [Research Institution] found that organizations that effectively communicate changes in data processing purposes and ensure compatibility with the original intent experience fewer legal challenges and maintain better relationships with their user base.

Navigating changes in data processing purposes requires a delicate balance between legal compliance, transparency, and user trust. Organizations must be aware of the legal consequences of purpose changes, obtain explicit consent when necessary, and adhere to the principles of compatibility. By approaching purpose changes with diligence and respect for privacy, organizations can adapt to evolving needs while maintaining the trust and confidence of their data subjects.

Night Depositories (What Are They And How They Work: Overview)

What Are Night Depositories?

Night depositories, also known as night drop boxes or night safes, are secure facilities provided by banks and financial institutions for customers to make deposits outside of regular banking hours. These facilities are especially useful for businesses that handle large amounts of cash or have busy schedules that make it difficult to visit the bank during regular operating hours.

Functionality

Night depositories typically consist of a secure, tamper-resistant container or safe installed in an exterior wall of the bank. Customers can use these depositories to deposit cash, checks, and other financial instruments securely. The process usually involves placing the deposit items into the night depository, and the bank retrieves and processes the deposits during the next business day.

Proven by Progress

The use of night depositories has a long history and has proven to be a reliable and convenient method for businesses and individuals to manage their banking needs outside of traditional banking hours. Here are some key aspects that highlight the effectiveness and progress of night depositories:

1. Convenience for Businesses:

Night depositories offer a practical solution for businesses that operate outside of regular banking hours. For example, restaurants, retail stores, and other businesses that handle a significant amount of cash can securely deposit their earnings without waiting for the bank to open.

2. Enhanced Security:

Night depositories are designed with security in mind. They are often equipped with features such as tamper-evident seals, heavy-duty construction, and advanced locking mechanisms to ensure the safety of deposited items.

3. Efficiency in Banking Operations:

From the bank’s perspective, night depositories contribute to operational efficiency. Instead of waiting for customers to make deposits during regular hours, banks can process night depository transactions in batches, streamlining their operations.

4. Technology Integration:

With technological advancements, some night depositories are equipped with advanced features such as real-time monitoring, digital imaging, and electronic notifications. This integration enhances the overall efficiency and security of the deposit process.

5. Regulatory Compliance:

Night depositories adhere to strict regulatory standards to ensure the integrity of the deposited items. Compliance with regulations such as the Bank Secrecy Act (BSA) and anti-money laundering (AML) requirements is crucial for the banking industry, and night depositories are designed to meet these standards.

Several financial experts and studies support the continued use and improvement of night depositories in the banking industry:

According to financial industry experts, night depositories remain a vital component of banking services, particularly for businesses with unique operational hours. They emphasize the importance of adapting these facilities to meet evolving security and technological standards.

2. Studies on Banking Trends:

Research studies on banking trends consistently highlight the enduring relevance of night depositories. The ability to make secure deposits at any time is seen as a customer-centric approach that aligns with the changing dynamics of modern business operations.

Night Depository Features

Night depositories, or night drop boxes, offer a range of features designed to ensure the security and convenience of after-hours deposits. Understanding these features is essential for businesses and individuals looking to utilize this service.

1. Secure Construction:

Night depositories are constructed with security in mind. They often feature heavy-duty materials, reinforced walls, and tamper-resistant designs to protect deposited items from theft or vandalism.

Example: Many night depositories are equipped with anti-fishing mechanisms, which prevent unauthorized individuals from retrieving items by manipulating the deposit slot.

2. Tamper-Evident Seals:

To provide an added layer of security, night depositories are sealed with tamper-evident seals. These seals are designed to show visible signs of tampering, ensuring the integrity of the deposited items.

Example: Banks commonly use numbered seals, and customers can verify the seal number matches their deposit receipt for added assurance.

3. Electronic Monitoring Systems:

Some modern night depositories are equipped with electronic monitoring systems. These systems may include surveillance cameras and sensors to detect any unusual activity near the depository.

Example: Banks can remotely monitor night depositories in real-time, enhancing security and enabling quick response to any potential issues.

4. Time-Locked Access:

Night depositories often have time-locked access mechanisms, restricting entry to specific time windows. This feature ensures that only authorized personnel can access the contents of the depository.

Example: Access to the night depository may be limited to bank employees during non-business hours, preventing unauthorized access.

How To Use Bank Night Deposit Box

Using a bank night deposit box or a drop safe is a straightforward process, and understanding the steps involved is crucial for a smooth transaction.

1. Prepare Your Deposit:

Organize your deposit items, including cash, checks, and any necessary documentation. Place them in a sealed envelope or bag for added security.

2. Visit the Bank:

Go to your bank’s location and locate the night deposit box. These boxes are often situated near the main entrance and are easily identifiable.

3. Complete the Deposit Slip:

Many night depositories require customers to fill out a deposit slip, providing essential information such as account number and the total amount of the deposit.

Expert Tip: Financial advisors recommend double-checking the deposit slip for accuracy to avoid processing errors.

4. Insert Deposit into the Night Depository:

Open the night deposit box using the provided access panel. Insert your prepared deposit envelope or bag into the secure container.

Expert Opinion: Financial experts emphasize the importance of securely sealing the deposit and ensuring it fits through the deposit slot without folding or damage.

5. Record the Transaction:

Keep a record of your deposit, including the date, time, and amount. This record can be essential for reconciling your accounts and resolving any discrepancies.

Night Deposit Safety Tips

Night deposit safety is paramount for individuals and businesses utilizing these services. Here are some crucial safety tips to ensure a secure night deposit experience:

1. Choose Well-Lit Locations:

Opt for night deposit boxes located in well-lit areas. Adequate lighting reduces the risk of theft or unauthorized activities during the deposit process.

Expert Tip: Security experts recommend choosing night deposit boxes that are visible from nearby surveillance cameras.

2. Be Mindful of Surroundings:

Before approaching the night deposit box, survey the surroundings. Ensure there are no suspicious individuals or activities that could pose a threat.

Example: Banks often provide exterior mirrors near night deposit boxes to help customers observe their surroundings before making a deposit.

3. Use Secure Packaging:

Package your deposits securely in tamper-evident envelopes or bags. This adds an extra layer of protection to your deposited items.

Security Measure: Some banks provide specialized deposit bags that have built-in security features, such as tear-resistant material and unique barcoding.

4. Avoid Routine Patterns:

Vary the times and days you make night deposits to avoid establishing predictable patterns. This makes it more challenging for potential criminals to target you.

Security Strategy: Financial advisors often recommend businesses to have multiple employees share the responsibility of making night deposits on a rotating schedule.

5. Check for Tampering:

Before making a deposit, inspect the night deposit box for any signs of tampering. Ensure that the security features, such as seals and locking mechanisms, are intact.

Expert Insight: Security professionals emphasize the importance of reporting any suspicious findings to the bank immediately.

Night Depository Agreement

Using a night deposit box often involves entering into a formal agreement with the bank. Understanding the terms and conditions is crucial for a smooth and secure deposit process.

1. Liability and Responsibility:

The night deposit agreement outlines the responsibilities and liabilities of both the depositor and the bank. It clarifies who bears the risk in case of loss or theft.

Legal Aspect: Legal experts stress the importance of carefully reading and understanding the liability clauses in the agreement to avoid misunderstandings.

2. Access Authorization:

The agreement specifies who has access to the night deposit box. Typically, only authorized personnel, such as bank employees, should have access during non-business hours.

Security Measure: Night deposit agreements often include provisions for revoking access immediately in case of employment termination or other changes.

3. Deposit Limits and Restrictions:

Limits on deposit amounts and types of accepted items may be outlined in the agreement. Understanding these limitations helps avoid complications during the deposit process.

Example: Some night deposit agreements may have restrictions on the size of deposits for security and processing efficiency.

4. Notification Procedures:

The agreement may detail the procedures for notifying the bank about deposited items, especially if there are discrepancies or issues with the transaction.

Best Practice: Financial advisors recommend keeping a copy of the deposit slip and notifying the bank promptly if there are any discrepancies in the processed deposit.

5. Changes and Amendments:

Night deposit agreements may include provisions for changes and amendments. It is essential to be aware of how and when the bank can modify the terms and conditions.

Legal Perspective: Legal experts suggest regularly reviewing the night deposit agreement and staying informed about any updates or changes communicated by the bank.

Night Depositories vs ATM

Night depositories and ATMs (Automated Teller Machines) serve different purposes but share some similarities. Understanding their differences is crucial for choosing the most suitable option for specific banking needs.

1. Purpose and Functionality:

Night depositories are primarily used for depositing funds, especially outside regular banking hours. ATMs, on the other hand, provide a range of services, including cash withdrawals, balance inquiries, and sometimes deposits.

Expert Opinion: Financial analysts emphasize that the choice between a night depository and an ATM depends on the specific banking transaction needs.

2. Depositing Process:

Night depositories involve depositing items into a secure container, usually outside the bank. ATMs, in contrast, often allow users to deposit checks and cash directly into the machine.

Example: Some advanced ATMs offer envelope-free cash and check deposits, providing a convenient alternative to night depositories.

3. Accessibility:

Night depositories may be limited to the exterior of a bank, and access is typically restricted during certain hours. ATMs, in contrast, are often available 24/7 in various locations.

Convenience Factor: ATMs provide a more accessible option for individuals who need to perform banking transactions at any time, day or night.

4. Transaction Limits:

Night depositories may have specific limits on the size and types of deposits. ATMs often have transaction limits for both withdrawals and deposits.

Best Practice: It’s important to be aware of transaction limits and choose the option that aligns with the size and frequency of transactions.

5. Security Features:

Both night depositories and ATMs are equipped with security features, but the nature of these features may differ. Night depositories focus on secure storage, while ATMs prioritize secure transactions.

Security Emphasis: Security experts suggest that individuals and businesses assess the specific security features relevant to their transaction needs when choosing between night depositories and ATMs.

Ensuring the safety of night deposit transactions involves adopting best practices, understanding the terms of the night deposit agreement, and considering the differences between night depositories and ATMs. By following these guidelines, individuals and businesses can make informed decisions to protect their financial interests and streamline their banking activities.

Deposit Drop Box Takeaways

Deposit drop boxes, also known as night depositories or deposit safes, offer individuals and businesses a convenient way to make secure deposits outside regular banking hours. Here are some key takeaways regarding these financial tools:

1. Convenience and Accessibility:

Deposit drop boxes provide unparalleled convenience for individuals and businesses with irregular schedules or those unable to visit the bank during standard operating hours. Their accessibility allows for the timely deposit of funds, checks, and important financial documents.

Example: A small business owner, working late into the evening, can use a deposit drop box to securely deposit the day’s earnings without waiting for the bank to open the next day.

2. Security Measures:

Deposit drop boxes are designed with robust security features to safeguard deposited items. These may include tamper-evident seals, time-locked access, surveillance cameras, and durable construction to prevent theft or vandalism.

Security Insight: Security experts often highlight the importance of choosing deposit drop boxes with the latest security features to ensure the protection of deposited assets.

3. Regulatory Compliance:

Financial institutions offering deposit drop box services adhere to stringent regulatory standards to ensure the legality and integrity of the deposited items. Compliance with regulations like the Bank Secrecy Act (BSA) and anti-money laundering (AML) requirements is imperative.

Fact: Banks regularly undergo audits and inspections to confirm compliance with financial regulations, providing an additional layer of assurance for depositors.

4. Record Keeping and Documentation:

Maintaining accurate records is crucial for both depositors and financial institutions. Users are often required to complete deposit slips with essential information, such as account numbers and deposit amounts, ensuring accurate tracking and processing.

Best Practice: Financial advisors recommend retaining copies of deposit slips and transaction records for personal or business financial records.

5. Technology Integration:

With advancements in technology, some deposit drop boxes are equipped with digital features such as real-time monitoring, electronic notifications, and imaging capabilities. These technological integrations enhance the overall efficiency and security of the deposit process.

Expert Opinion: Industry experts suggest that the integration of technology in deposit drop boxes not only improves security but also streamlines banking operations.

6. Flexibility in Deposit Types:

Deposit drop boxes are not limited to cash; they often accept checks, money orders, and other financial instruments. This flexibility makes them versatile tools for a wide range of depositors with varying financial needs.

Example: A customer can use a deposit drop box to securely deposit a mix of cash and checks, catering to diverse financial transactions.

7. Educating Users on Best Practices:

Financial institutions often provide guidelines and educate users on best practices for utilizing deposit drop boxes. This includes tips on secure packaging, avoiding routine patterns, and being vigilant about surroundings during the deposit process.

Educational Initiatives: Banks may conduct workshops or distribute informational materials to ensure users are well-informed about the proper use of deposit drop boxes.

8. Evolution Over Time:

Deposit drop boxes have evolved to meet the changing needs of depositors. From manual drop boxes to technologically advanced solutions, the evolution reflects a commitment to providing efficient and secure deposit options.

Historical Context: Early deposit drop boxes were simple receptacles, but today, many are equipped with cutting-edge features, showcasing the adaptability of these tools.

Deposit drop boxes offer a range of benefits, including convenience, security, and flexibility. As financial institutions continue to invest in technological advancements and regulatory compliance, deposit drop boxes remain a vital component of modern banking, providing users with a secure and efficient way to manage their deposits beyond regular banking hours. Understanding the key takeaways ensures that individuals and businesses can make the most of these financial tools while prioritizing the safety and efficiency of their financial transactions.
Leveraging CapCut’s Multimedia Resources for Stunning Content

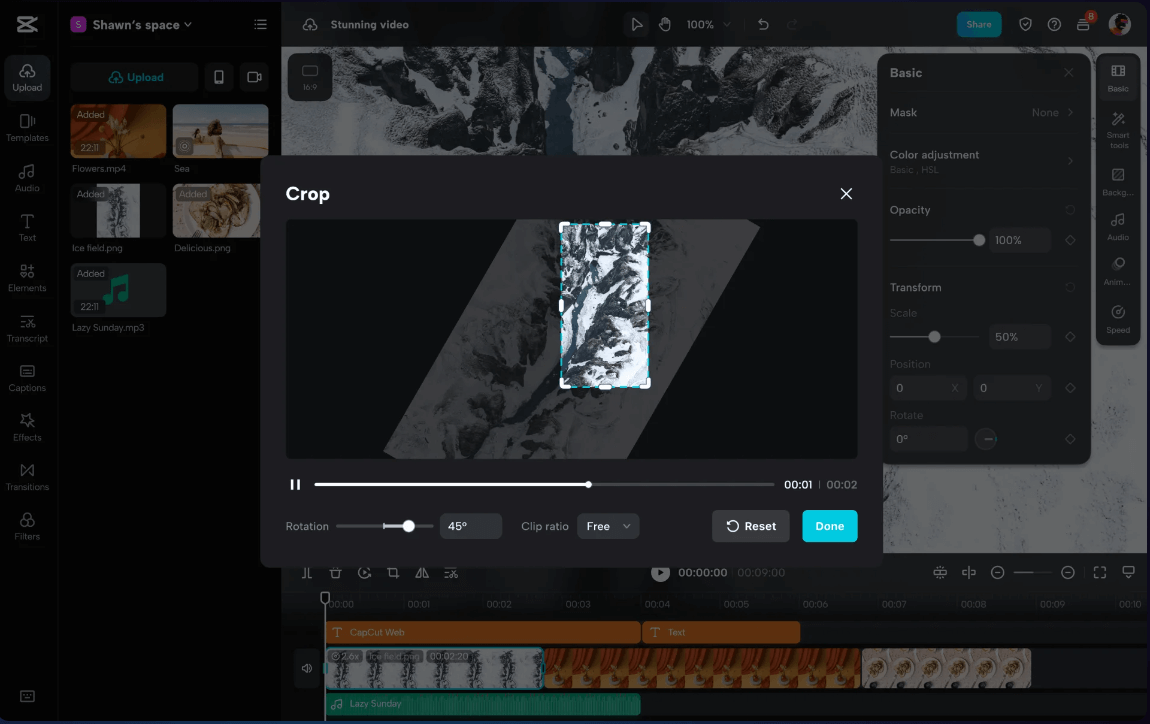
In today’s fast-paced digital landscape, content creators are continually on the lookout for versatile and innovative tools to enhance their creative projects. Among the array of options available, CapCut’s Creative Suite has emerged as a dynamic toolkit, empowering content creators in their quest to produce captivating and visually stunning content, along with performing various tasks such as add subtitle to video, etc. This comprehensive guide delves deep into the wealth of multimedia resources offered by CapCut’s Creative Suite. From images and videos to audio elements, we’ll explore how this toolkit provides creators with a wellspring of resources to transform their creative visions into stunning realities.

The Power of Multimedia Resources 

Multimedia resources are the lifeblood of visual content creation. In this section, we will uncover the extensive library of multimedia assets available within CapCut’s Creative Suite. We’ll explore the wide range of images, videos, and audio elements that creators can readily access and integrate into their projects. These resources serve as the building blocks for crafting visually compelling content.

CapCut’s Creative Suite houses a vast repository of multimedia resources that form the cornerstone of creative projects. These resources span a diverse range of images, videos, and audio elements, offering content creators a treasure trove to draw upon. Whether you’re crafting a video, designing graphics, or adding audio to your project, the abundance of multimedia resources ensures that you have the building blocks needed to bring your creative vision to life.

With a multitude of multimedia resources at your fingertips, you can unlock your creativity and embark on a journey of limitless possibilities. The variety of assets available caters to a wide spectrum of creative needs, from visually stunning images that enhance your visual storytelling to videos that bring motion and life to your projects. Audio elements, on the other hand, enrich the auditory experience of your content, making it engaging and immersive.

In addition to the sheer volume of multimedia resources, CapCut’s Creative Suite offers powerful search and organization tools. You can easily locate the perfect image, video clip, or audio segment to complement your project. Moreover, the suite’s intuitive organization features enable you to manage and categorize your resources efficiently, ensuring that you can access what you need when you need it.

Whether you’re a professional content creator or a novice starting your creative journey, CapCut’s multimedia resources level the playing field. They provide you with the creative building blocks necessary to craft visually stunning content, share compelling narratives, and captivate your audience. The power of these resources lies not only in their abundance but also in their ability to catalyze your creativity and drive your projects to new heights.

Crafting Engaging Visual Stories 

Visual storytelling is at the heart of multimedia content, and this section will focus on how content creators can leverage CapCut’s multimedia resources to craft engaging narratives. We’ll discuss techniques for selecting the right images and videos, incorporating them seamlessly into projects, and the role of audio elements in enhancing the overall storytelling experience.

The ability to craft engaging visual stories is a cornerstone of content creation, and CapCut’s multimedia resources are essential ingredients in this process. Whether you’re producing a video, designing graphics, or adding visual elements to your project, the art of storytelling relies heavily on the images and videos you incorporate.

Selecting the Right Images and Videos: The art of storytelling begins with choosing the right images and videos to convey your message. CapCut’s vast collection offers an array of choices, allowing you to pick visuals that align with your narrative. Whether it’s a poignant photograph, a captivating video clip, or a sequence of images, the key is to select resources that resonate with your storytelling objectives.

Incorporating Resources Seamlessly: Once you’ve chosen your images and videos, the next step is to seamlessly integrate them into your project. CapCut’s user-friendly interface simplifies this process, ensuring that you can effortlessly arrange and edit your chosen resources. Whether you’re crafting a video, presentation, or graphic design, the toolkit’s features facilitate smooth integration, enabling you to tell your story with finesse.

Enhancing the Auditory Experience: While visual elements are crucial, audio elements also play a significant role in storytelling. CapCut’s multimedia resources extend to audio, providing you with a wide range of sounds and music to enhance the auditory dimension of your content. From adding background music to incorporating sound effects, audio elements enrich your narrative and make it more immersive.

With CapCut’s multimedia resources, you have the creative assets required to craft compelling and engaging visual stories. The toolkit’s extensive library of images, videos, and audio elements empowers you to select the perfect resources that align with your storytelling objectives. Moreover, the user-friendly interface ensures that you can seamlessly incorporate these resources into your project, bringing your narrative to life with finesse and impact.

Conclusion 

CapCut’s Creative Suite offers a treasure trove of multimedia resources that empower content creators to elevate their creative projects. From images and videos to audio elements, this toolkit provides the essential building blocks for crafting visually stunning content. By harnessing the power of multimedia resources, content creators can weave engaging visual stories, customize resources to fit their creative visions, and streamline their workflow for maximum efficiency. With CapCut’s multimedia resources at their disposal and a free cloud storage option at hand, content creators are equipped to captivate audiences with their compelling narratives.

In a world driven by visual content, the multimedia resources available in CapCut’s Creative Suite play a pivotal role in enhancing creativity, boosting efficiency, and bringing creative visions to life. As content creators continue to push the boundaries of what’s possible, these resources provide the tools to explore new horizons and captivate audiences in exciting and innovative ways. With the power of CapCut’s multimedia resources, content creators can unlock their full creative potential and redefine the standards of visual storytelling.

Adding Someone to a Deed with a Mortgage

Adding someone to a deed with a mortgage is a significant legal and financial decision that involves several considerations. While a mortgage is a loan used to purchase a property, a deed is a legal document that establishes ownership. When someone is added to a deed with a mortgage, they become a co-owner of the property. This process is often referred to as adding a co-borrower or co-owner to the property.

One primary reason for adding someone to a deed with a mortgage is to share ownership and potentially the financial responsibility for the property. This is common in situations such as marriage, partnerships, or familial relationships where individuals want to jointly own the property. It’s essential to note that adding someone to the deed doesn’t automatically make them responsible for the mortgage; that responsibility is typically tied to the loan agreement.

However, it’s crucial to understand the implications of such a decision. In case the mortgage payments are not made, the lender can still pursue the original borrower for payment, even if they are not listed on the deed. Therefore, a clear agreement between co-owners outlining their financial responsibilities is crucial.

In situations where a family member or friend is being added to the deed, it’s advisable to consult with legal and financial professionals to ensure that all parties involved are aware of the legal and financial implications. Proper documentation and legal advice can help avoid potential conflicts and ensure a smooth process.

Can a Girlfriend’s Name Be on a Deed and Not on the Mortgage?

The question of whether a girlfriend’s name can be on a deed without being on the mortgage is complex and depends on various factors, including legal and financial considerations. Generally, it is possible for someone to be on the deed without being on the mortgage, but it raises important questions about ownership and financial responsibility.

When a person’s name is on the deed, they have a legal claim to ownership of the property. However, the mortgage is a separate financial agreement that determines who is responsible for repaying the loan. In many cases, mortgage lenders require individuals listed on the deed to also be on the mortgage, as this provides them with a legal claim to the property in case of default.

If a girlfriend’s name is on the deed but not on the mortgage, it means she has an ownership interest in the property but is not legally obligated to repay the mortgage. This arrangement could lead to potential complications, especially if the relationship sours or if there are disagreements about financial responsibilities.

Legal experts emphasize the importance of clear communication and written agreements in such situations. It’s advisable to consult with legal professionals to draft a legally binding agreement that outlines each party’s rights and responsibilities regarding the property. This agreement can address issues such as financial contributions, mortgage payments, and what happens in the event of a breakup or sale of the property.

It’s crucial to be aware that laws regarding property ownership and mortgages can vary, so seeking legal advice specific to the jurisdiction is essential.

Title Deed Vs. Mortgage

Understanding the difference between a title deed and a mortgage is fundamental for anyone involved in real estate transactions. These two legal documents serve distinct purposes in the property ownership process.

A title deed, also known simply as a deed, is a legal document that transfers ownership of real property from one party to another. It contains a detailed description of the property and identifies the buyer (grantee) and the seller (grantor). Once the title deed is recorded with the appropriate government office, it becomes a public record, providing evidence of ownership.

On the other hand, a mortgage is a financial agreement between a borrower and a lender to finance the purchase of a property. The mortgage gives the lender a security interest in the property, allowing them to take possession if the borrower fails to repay the loan. The borrower, in turn, has the legal obligation to make regular mortgage payments.

One key distinction is that the title deed establishes ownership, while the mortgage creates a security interest for the lender. In most cases, the title deed is held by the property owner, while the mortgage is held by the lender until the loan is fully repaid.

It’s important to note that the title deed and mortgage are interconnected in a real estate transaction. The title deed is transferred to the buyer upon the sale, and the mortgage is used to secure the financing for that purchase. However, when the mortgage is fully repaid, the lender releases their interest in the property, and the title deed remains as the sole proof of ownership.

The title deed is the legal document that establishes ownership, while the mortgage is a financial agreement that provides security for the lender. Both are critical components of a real estate transaction, and understanding their roles can help individuals navigate the complexities of property ownership and financing.

Names on the Title Deed of A House

Understanding the significance of having your name on the title deed of a house is crucial for anyone navigating the realm of real estate ownership. The title deed is a legal document that serves as proof of ownership and outlines who has the right to possess and use the property. Having your name on the title deed establishes your legal claim to the property and provides a basis for various property-related transactions.

When your name is on the title deed, it signifies that you have an ownership interest in the property. This document typically includes details such as the property’s legal description, the names of the owners (grantees), and the details of how the property was acquired. The title deed is recorded with the appropriate government office, making it a public record accessible to interested parties.

Having your name on the title deed is not just a matter of ownership; it also plays a crucial role in financial transactions related to the property. When selling the property or using it as collateral for a loan, the title deed is a primary document that establishes your legal right to do so. Additionally, in case of inheritance or estate planning, the title deed becomes a key document that determines the transfer of ownership.

Experts recommend that individuals regularly check the title deed to ensure that the information is accurate and up-to-date. Any discrepancies or errors should be addressed promptly to avoid potential legal and financial complications in the future.

Adding your Girlfriend To A Deed With A Mortgage

Adding a girlfriend to a deed with a mortgage is a decision that involves legal, financial, and relationship considerations. While it is technically possible to add someone to the deed without them being on the mortgage, this can lead to complex situations and potential challenges.

When a person is added to the deed, they gain a legal ownership interest in the property. However, the mortgage is a separate financial agreement that outlines the responsibility for repaying the loan. If the girlfriend is not on the mortgage but is on the deed, she gains ownership rights without being legally obligated to contribute to mortgage payments. This can create complications if the relationship sours or if there are disagreements about financial responsibilities.

Legal and financial experts stress the importance of clear communication and a written agreement when making such decisions. A well-drafted agreement can address issues such as financial contributions, mortgage payments, and what happens in the event of a breakup or sale of the property. Consulting with legal professionals to ensure that the agreement complies with local laws and regulations is advisable.

It’s essential to be aware that adding someone to the deed may have tax implications, and seeking advice from tax professionals can help navigate potential issues. Additionally, understanding the laws and regulations governing property ownership and mortgages in the specific jurisdiction is crucial for making informed decisions.

If there is a loan on my property, can I add someone to the deed?

The question of whether you can add someone to the deed when there is a loan on the property involves a nuanced analysis of legal and financial considerations. Generally, it is possible to add someone to the deed even if there is an existing loan on the property, but it’s essential to understand the implications of such a decision.

The addition of someone to the deed doesn’t automatically make them responsible for the mortgage. The mortgage is a separate financial agreement between the borrower and the lender, and adding a person to the deed doesn’t affect this contractual relationship. The original borrower remains responsible for making mortgage payments, and the lender has a claim on the property in case of default.

However, adding someone to the deed can have implications for the lender. Lenders typically include a “due-on-sale” clause in mortgage agreements, which means that if there is a change in ownership, they have the right to accelerate the loan and demand full repayment. While this doesn’t necessarily mean the lender will call the loan due immediately, it is a factor that should be considered.

Before adding someone to the deed when there is an existing loan, it’s crucial to review the mortgage agreement and consult with the lender. Some lenders may allow the addition of a person to the deed, while others may have restrictions or requirements. Legal and financial professionals can provide guidance on the specific steps to take and ensure compliance with all relevant laws and regulations.

Adding someone to the deed with an existing loan is possible, but it requires careful consideration of the mortgage agreement, lender policies, and legal implications. Seeking professional advice is recommended to navigate this process successfully.

If I add someone to title, does that make them responsible for the loan as well?

The relationship between adding someone to the title of a property and their responsibility for the loan is a crucial consideration in real estate transactions. Generally, adding someone to the title does not automatically make them responsible for the loan associated with the property.

When someone is added to the title, it means they gain a legal ownership interest in the property. However, the loan or mortgage associated with the property is a separate financial agreement between the borrower and the lender. Adding an individual to the title doesn’t change the terms of the loan or create a direct obligation for the newly added person to repay the mortgage.

The original borrower remains responsible for the mortgage, and the lender’s primary concern is ensuring that the loan is repaid according to the terms outlined in the mortgage agreement. Even if another person is added to the title, the lender typically retains the right to pursue the original borrower in case of default.

It’s crucial for individuals considering adding someone to the title to be aware of the legal and financial implications. Clear communication and a comprehensive written agreement between the parties involved can help delineate responsibilities, especially regarding mortgage payments. Seeking legal advice before making such decisions is advisable to ensure that all parties understand their rights and obligations.

Adding someone to the title of a property does not automatically make them responsible for the loan, but it’s essential to have a clear understanding of the legal and financial implications and to establish agreements accordingly.

Without adding someone to the title of my property, is there another way to name the person I want to have my property in the event of my death?

Naming someone to inherit your property without adding them to the title involves utilizing estate planning tools that allow for a seamless transfer of assets upon your death. One common method is through a will, and another is by establishing a living trust.

  1. Will: A will is a legal document that outlines your wishes for the distribution of your assets after your death. In the context of real estate, you can specify in your will who you want to inherit your property. However, it’s important to note that the property will likely go through the probate process, which can be time-consuming and may involve court costs. Nevertheless, a will provides a straightforward way to name beneficiaries for your property without adding them to the title during your lifetime.
  2. Living Trust: A living trust is a legal entity that holds and manages your assets during your lifetime and can continue to do so after your death. When you establish a living trust, you transfer ownership of your property to the trust. As the trustee, you maintain control over the property, but you also name successor trustees who will take over management and distribution of the assets after your death. The living trust allows for a smoother transfer of assets without going through probate.

Estate planning experts often recommend a combination of these tools, depending on individual circumstances. The choice between a will and a living trust can depend on factors such as the size of the estate, the desire for privacy, and the complexity of asset distribution.

Legal professionals specializing in estate planning can provide personalized advice and help individuals tailor their plans to ensure that their property is passed on according to their wishes. Regularly updating these documents is also crucial to reflect changes in personal circumstances or changes in the law.

There are alternative methods, such as wills and living trusts, to name someone as the inheritor of your property without adding them to the title during your lifetime. Seeking professional advice and having a well-thought-out estate plan can provide peace of mind and help streamline the transfer of assets to your chosen beneficiaries.

How Long Does It Take to Record a Deed?

The timeline for recording a deed can vary based on several factors, including the efficiency of the local recording office and the volume of transactions. Generally, the process involves submitting the deed to the county recorder or clerk’s office where the property is located. Once submitted, the recording office reviews the document for completeness and compliance with legal requirements.

In many jurisdictions, the recording process takes a few days to several weeks. However, some areas offer expedited services for an additional fee, which can significantly reduce the recording time. It’s essential to check with the local recording office to get accurate information on processing times and any available expedited options.

The recording of a deed is a crucial step in the real estate transaction process. Until the deed is officially recorded, the transfer of ownership may not be legally recognized. Delays in recording can impact subsequent transactions or the ability to prove ownership.

Real estate professionals often emphasize the importance of promptly recording deeds to ensure a smooth and legally sound transfer of property. Delays in recording may also expose the parties involved to potential legal and financial risks. It’s advisable to work closely with a knowledgeable real estate attorney or title company to navigate the recording process efficiently.

Am I Responsible for Recording the Deed?

The responsibility for recording a deed typically falls on the party responsible for preparing the document. In many real estate transactions, this responsibility lies with the seller or the seller’s attorney. However, the specific arrangements can be negotiated and outlined in the purchase agreement or closing documents.

While the seller often takes the lead in preparing and submitting the deed for recording, buyers can play an active role in ensuring the process is completed accurately and in a timely manner. Collaborating with a real estate attorney or a title company can provide guidance on the necessary steps and help navigate any legal requirements associated with the recording process.

Buyers and sellers should communicate clearly and confirm the party responsible for recording the deed as part of the transaction negotiations. Once the responsibility is established, it’s crucial to follow up to ensure the deed is submitted promptly after the closing.

In some cases, buyers may choose to take on the responsibility of recording the deed to have more control over the process. However, this should be clearly communicated and agreed upon by all parties involved.

It’s important to note that the recording fee, which covers the cost of officially documenting the deed, is typically a buyer’s closing cost. This fee may vary depending on the jurisdiction and local recording office.

What Requirements Must a Deed Meet to Be Properly Recorded?

To be properly recorded, a deed must meet specific legal and procedural requirements set by the jurisdiction’s recording office. While these requirements can vary, there are common elements that deeds must typically include:

  1. Legal Description: The deed must contain a accurate and detailed legal description of the property being transferred. This description is crucial for identifying the boundaries and location of the property.
  2. Grantor and Grantee Information: The names and addresses of the grantor (the person transferring the property) and the grantee (the person receiving the property) must be clearly stated in the deed.
  3. Notary Acknowledgment: The deed must include a notary acknowledgment, where the grantor acknowledges their signature in the presence of a notary public. This helps ensure the authenticity of the document.
  4. Consideration or Value: The deed should specify the consideration exchanged for the property, which is typically the purchase price. Some jurisdictions may require this information for tax purposes.
  5. Execution Date: The deed must have a date indicating when it was executed or signed by the parties involved.
  6. Recording Fee: The appropriate recording fee must be paid when submitting the deed for recording. The amount can vary based on the jurisdiction.

Meeting these requirements is essential for the deed to be legally valid and properly recorded. Additionally, it’s crucial to check with the local recording office for any specific requirements or forms that may be unique to the jurisdiction.

Real estate professionals, including attorneys and title companies, play a key role in ensuring that deeds meet all necessary requirements for recording. Working with experienced professionals can help prevent delays and legal complications in the recording process.

What Happens If the Deed Wasn’t Recorded Properly?

Properly recording a deed is a critical step in the real estate transaction process, and failure to do so can have significant legal and financial consequences. When a deed isn’t recorded properly, it may lead to complications in establishing and proving ownership of the property.

  1. Clouded Title: One common consequence of improperly recorded deeds is a clouded title. A cloud on the title refers to any potential issue that may cast doubt on the ownership of the property. This could arise if there are conflicting claims or if the chain of ownership is unclear due to a failure to record the deed.
  2. Inability to Transfer Ownership: Proper recording is essential for legally transferring ownership of the property. If the deed is not recorded, subsequent buyers may face challenges in proving their ownership rights, and the property’s marketability may be compromised.
  3. Legal and Financial Risks: The failure to record a deed may expose the parties involved to legal and financial risks. For example, if a buyer purchases a property without a properly recorded deed, they may not have clear ownership rights and could be vulnerable to legal disputes.
  4. Title Insurance Issues: Title insurance is often contingent on a properly recorded deed. If the deed is not recorded, it may affect the coverage provided by title insurance, leaving the property owner without protection against certain title defects.

To avoid these complications, it’s crucial to follow the proper procedures for recording deeds in the jurisdiction where the property is located. Working with experienced real estate professionals, such as attorneys or title companies, can help ensure that the recording process is handled correctly.

How Do I Know If the Deed Has Been Properly Recorded?

Verifying whether a deed has been properly recorded is essential for property owners to ensure the legitimacy of their ownership. Several steps can be taken to confirm the proper recording of a deed:

  1. Check the County Recorder’s Office: The first step is to contact the county recorder’s office in the jurisdiction where the property is located. Many recorder’s offices have online databases that allow individuals to search for recorded documents, including deeds. By providing the relevant details, such as the names of the grantor and grantee, one can confirm if the deed is on record.
  2. Request a Copy of the Recorded Deed: Property owners can request a copy of the recorded deed from the county recorder’s office. This official document serves as proof that the deed has been properly recorded and is part of the public record.
  3. Use a Title Company or Real Estate Attorney: Title companies and real estate attorneys often conduct thorough title searches as part of the closing process. These professionals can provide assurance regarding the proper recording of the deed and offer guidance on any potential issues.
  4. Review the Closing Documents: During the closing of a real estate transaction, various documents are signed, including the deed. Reviewing the closing documents can help confirm whether the deed was prepared, signed, and submitted for recording.

What Do I Do If My Deed Wasn’t Recorded?

If you discover that your deed wasn’t recorded properly, taking immediate action is crucial to mitigate potential legal and financial risks. Here are steps to consider:

  1. Contact the County Recorder’s Office: Reach out to the county recorder’s office to inquire about the reason for the non-recording. It could be a simple administrative error that can be rectified.
  2. Re-Record the Deed: In many cases, you can re-record the deed by resubmitting it to the county recorder’s office. Ensure that any errors or issues identified during the initial attempt are addressed before resubmitting.
  3. Consult with Legal Professionals: Seek advice from real estate attorneys or title professionals who can guide you through the process of correcting the recording. They can help ensure that all necessary steps are taken to remedy the situation.
  4. Consider Title Insurance Claims: If you have title insurance, contact the insurance provider to discuss the situation. Title insurance may provide coverage for certain issues related to the recording of deeds.
  5. Document and Preserve Evidence: Keep detailed records of all communications, documents, and actions taken to address the issue. This documentation may be valuable if legal disputes arise in the future.

Prevention is key, and working with experienced professionals during the real estate transaction process can help avoid common pitfalls related to the recording of deeds. Regularly checking the status of recorded documents and promptly addressing any issues ensures the integrity of property ownership.

The Most Successful Immigrants in the United States

Immigration has played a pivotal role in shaping the United States, contributing to its diversity and economic vitality. Over the years, many immigrants have achieved remarkable success in various fields, making significant contributions to American society. Here, we explore some examples of the most successful immigrants in the United States.

  1. Elon Musk (South Africa/Canada): One of the most iconic entrepreneurs of our time, Elon Musk, was born in South Africa and later became a Canadian citizen before ultimately moving to the United States. Musk co-founded companies like PayPal, Tesla, and SpaceX. His ventures have not only transformed industries but have also significantly impacted the global economy. Musk’s story highlights the role of immigrants in driving innovation and economic growth.
  2. Andrew Carnegie (Scotland): A philanthropist and industrialist, Andrew Carnegie, immigrated to the United States from Scotland in the mid-19th century. He became a leading figure in the American steel industry and eventually one of the wealthiest individuals of his time. Carnegie’s dedication to philanthropy led to the funding of numerous libraries, universities, and cultural institutions, leaving a lasting legacy.
  3. Madeleine Albright (Czechoslovakia): Born in Czechoslovakia, Madeleine Albright became the first female U.S. Secretary of State. Her family sought asylum in the United States during World War II, escaping the Nazi occupation. Albright’s diplomatic career was marked by her efforts to promote democracy and human rights on the global stage. Her achievements underscore the impact immigrants can have on shaping U.S. foreign policy.
  4. Sundar Pichai (India): Sundar Pichai, born in India, is the Chief Executive Officer of Alphabet Inc., Google’s parent company. Pichai joined Google in 2004 and played a key role in developing products like Google Chrome and Google Drive. His journey from humble beginnings in India to leading one of the world’s most influential tech companies exemplifies the opportunities the U.S. provides to immigrants.
  5. Gloria Estefan (Cuba): Fleeing political turmoil in Cuba, Gloria Estefan and her family sought refuge in the United States. Estefan became a global icon in the music industry, known as the “Queen of Latin Pop.” Her success not only broke cultural barriers but also demonstrated the cultural richness that immigrants bring to the American landscape.

Factors Contributing to Immigrant Success

Several factors contribute to the success of immigrants in the United States:

  1. Education: Many successful immigrants emphasize the importance of education in their journeys. The U.S. education system provides opportunities for individuals to pursue academic and professional excellence.
  2. Entrepreneurship: Immigrants are often driven by a strong entrepreneurial spirit. Many successful immigrants have founded or led innovative companies, contributing to economic growth and job creation.
  3. Diversity of Skills and Perspectives: Immigrants bring diverse skills, experiences, and perspectives, enriching American society and fostering creativity and innovation.
  4. Resilience and Determination: Overcoming challenges is a common theme among successful immigrants. The resilience and determination to build a better life contribute to their accomplishments.

Expert Opinions and Studies

  1. National Academies of Sciences, Engineering, and Medicine Report: According to a comprehensive report by the National Academies, immigrants have had an overall positive effect on the U.S. economy, contributing to economic growth, innovation, and job creation.
  2. The Economic and Fiscal Consequences of Immigration (National Bureau of Economic Research): Research from the National Bureau of Economic Research suggests that immigrants have a positive impact on the U.S. economy by increasing productivity, contributing to technological innovation, and filling gaps in the labor market.

The success stories of immigrants in the United States highlight the nation’s capacity to harness the talents and contributions of individuals from diverse backgrounds.

One key aspect to reach success as an immigrant should be contacting an experienced lawyer such as Austin immigration lawyers, J. Sparks Law, PLLC, who will help you smooth all the necesary procedures.

The experiences of Elon Musk, Andrew Carnegie, Madeleine Albright, Sundar Pichai, and Gloria Estefan underscore the significance of immigration in shaping the cultural, economic, and innovative landscape of the United States. Embracing and supporting immigrants continues to be a vital aspect of the nation’s growth and prosperity.

Guaranty vs Guarantee

Understanding the difference between “guaranty” and “guarantee” is essential, as these terms are often used interchangeably but have distinct meanings in the legal and financial context.

Guarantee

A guarantee is a noun that refers to a promise or assurance given by one party to another. It is a commitment to stand behind a particular outcome, ensuring that a specific condition is met or a debt is fulfilled. Guarantees are commonly used in various contexts, such as product warranties, where a manufacturer guarantees the quality of their product for a specified period.

Example: A company offers a 100% satisfaction guarantee on its products, promising customers a refund if they are not satisfied.

Guaranty

On the other hand, “guaranty” is a noun that specifically refers to a pledge or assurance to take responsibility for another party’s debt or performance. In legal and financial contexts, a guaranty is a document outlining this commitment, often used in loan agreements or contracts where a third party (guarantor) guarantees to fulfill the obligations of the borrower if they default.

Example: When obtaining a business loan, a small business owner may need a personal guaranty from themselves or another individual, ensuring the lender that the loan will be repaid even if the business faces financial challenges.

Guarantee vs. Guaranty – What’s the Difference?

The primary difference between “guarantee” and “guaranty” lies in their usage and the context in which they are applied.

  • Guarantee (Noun and Verb):
    • Noun: It refers to a promise or assurance. Example: The warranty provides a guarantee of quality for the product.
    • Verb: It means to provide an assurance or make a promise. Example: The company guarantees that the repair will be completed within 48 hours.
  • Guaranty (Noun):
    • It specifically refers to a pledge or promise to take responsibility for another’s debt or performance. Example: The bank required a personal guaranty from the business owner to secure the loan.

In legal and financial documents, the term “guaranty” is more commonly used, as it denotes a specific type of commitment related to financial obligations.

What is the Difference Between Guarantee and Guaranty?

The difference between guarantee and guaranty is nuanced and pertains to their usage within different contexts.

  1. Legal Implications:
    • Guarantee: Generally used for broader assurances and promises.
    • Guaranty: Specifically used in legal and financial documents related to the assumption of another’s debt or obligations.
  2. Scope of Application:
    • Guarantee: Applicable in various contexts, including quality assurances and promises in non-financial agreements.
    • Guaranty: Primarily used in the context of financial agreements, loans, and contracts where one party assumes responsibility for another’s obligations.
  3. Grammatical Role:
    • Guarantee: Functions both as a noun and a verb.
    • Guaranty: Primarily used as a noun to describe a specific type of commitment.

Expert Opinions and Legal Perspectives:

  1. Legal Dictionary Definitions:
    • According to legal dictionaries, “guaranty” is defined as a pledge to answer for the debt or default of another, while “guarantee” is more broadly defined as a promise or assurance.
  2. Lawyers and Contract Experts:
    • Legal professionals emphasize the importance of precision in language when drafting contracts. Using “guaranty” when referring to a financial commitment helps avoid ambiguity in legal documents.

While guarantee and guaranty are related terms, their usage differs based on the context. Understanding the distinction is crucial for effective communication in legal, financial, and contractual matters, ensuring that commitments and obligations are accurately conveyed and understood by all parties involved.

When to Use Guarantee – Guarantee Definition

The term “guarantee” is commonly used in various contexts, and understanding when to use it is essential for clear and effective communication. The term functions both as a noun and a verb, and its usage depends on the nature of the assurance or promise being made.

Guarantee as a Noun: When used as a noun, a guarantee refers to a promise or assurance, often providing a specific level of certainty or confidence in a particular outcome. For example, a product warranty serves as a guarantee, assuring consumers that the product will meet certain quality standards, and if it doesn’t, the manufacturer will repair or replace it.

Example: The company offers a money-back guarantee if the customer is not satisfied with the product.

Guarantee as a Verb: As a verb, “guarantee” is used to express the act of providing assurance or making a promise. In contractual or service-oriented agreements, this term emphasizes a commitment to delivering on specified terms.

Example: The contractor guarantees the completion of the construction project within the agreed-upon timeframe.

Understanding when to use “guarantee” involves recognizing situations where a commitment or assurance is being offered, either as a noun or a verb.

When to Use Guaranty – Guaranty Definition

The term “guaranty” is more specialized and is primarily used in legal and financial contexts. Unlike “guarantee,” which is more versatile, “guaranty” specifically refers to a promise or pledge to answer for the debt or default of another party. This term is often used in contracts, loan agreements, or any situation where one party assumes responsibility for the obligations of another.

Example: The business owner provided a personal guaranty to secure a loan for the company.

Trick to Remember the Difference

To remember the difference between “guarantee” and “guaranty,” consider their contexts and applications:

  1. Versatility:
    • Guarantee: More versatile, applicable in various contexts beyond legal and financial agreements.
    • Guaranty: Primarily used in legal and financial contexts, particularly in situations involving the assumption of debt or obligations.
  2. Legal Connotations:
    • Guarantee: May have legal implications but is not exclusive to legal agreements.
    • Guaranty: Specifically used in legal and financial agreements, often involving a third party assuming responsibility.

Expert Opinions and Language Experts:

  1. Grammarly Insights:
    • According to Grammarly, “guarantee” is a more common and versatile term used in everyday language, while “guaranty” is more specific and used in formal or legal contexts.
  2. Merriam-Webster Dictionary:
    • Merriam-Webster defines “guarantee” as an assurance of the quality of a product or the fulfillment of a condition and “guaranty” as a pledge to pay another’s debt or to perform another’s duty in case of financial default or nonperformance.

Understanding when to use “guarantee” versus “guaranty” involves recognizing the contexts in which these terms are applied. “Guarantee” is versatile, used in various settings, while “guaranty” is more specialized, specifically employed in legal and financial agreements. The trick to remember the difference lies in considering the versatility and legal connotations of each term.